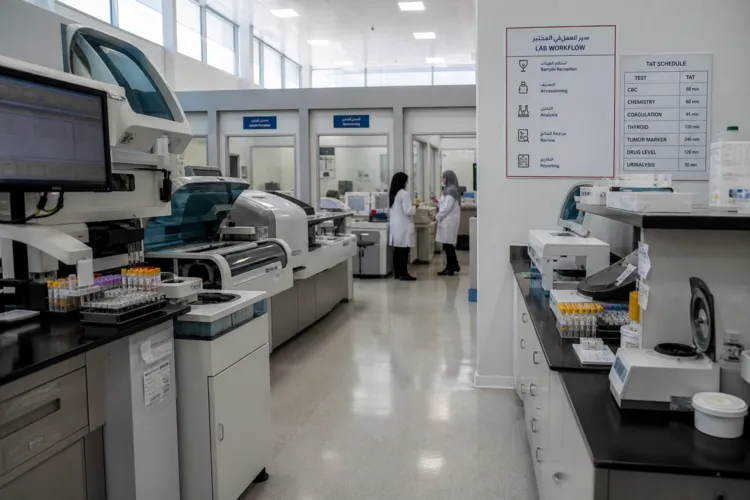
Healthcare is among the most active and attractive sectors for private equity investment in Saudi Arabia. Invest Riyadh values the Kingdom’s healthcare market at approximately SAR 200 billion (about $53 billion) and describes annual growth of 8% to 10%. The investment case is reinforced by policy and system redesign. The Ministry of Health operates about 280 hospitals and over 2,300 primary healthcare centers, while the private sector operates about 180 hospitals and over 3,000 clinics and medical centers. Total government healthcare expenditure exceeds SAR 100 billion annually, underscoring why professional capital is focused on assets that can be scaled, upgraded, and integrated.
The near-term deal logic sits inside national targets to expand private participation. Saudi Healthcare Private Equity Deal Flow Analysis notes that in 2024 the Saudi government allocated SAR 214 billion (about USD 57.1 billion) to healthcare, representing about 17% of its total budget. Multiple sources cite a stated goal to raise the private sector contribution from 25% to 35% by 2030. Vision2030.ai frames what it would take to meet that target: achieving a 35% private-sector share by 2030 requires approximately doubling private hospital bed capacity and substantially expanding outpatient care infrastructure, implying cumulative private healthcare capital investment of SAR 60 to 80 billion over the period.
Where Investors Find Platforms: Beds, Clinics, and the Payor Layer
In provider markets, consolidation and “platform building” are shaped by capacity constraints and competitive pressure. Dr. Saleh Al-Daghreer reports that total hospitals reached 500 in 2023, with only about 30% private, and that Saudi Arabia had 2.1 hospital beds per 1,000 people (2021). The same source cites expert estimates that the country needs 27,000 additional hospital beds by 2030. It also describes how mid-sized private facilities, often multi-specialty polyclinics with fewer than 100 beds, are squeezed between small specialist clinics and expanding large hospital groups. For investors, this supports strategies focused on acquiring fragmented assets, improving governance and operations, and creating referral networks that defend volume while meeting higher standards.
Insurance structure also influences how healthcare platforms monetize and expand. Deal Flow Analysis cites Mordor Intelligence, valuing the Saudi Arabia health and medical insurance market (premium value) at USD 10.53 billion in 2025, with estimates rising from USD 11.41 billion in 2026 to USD 16.12 billion by 2031 at a 7.16% CAGR. In 2025, group health led with a 71.33% share, inpatient cover accounted for 67.44%, and co-operative Takaful held 85.39%. The same source notes that real-time e-claims through the NPHIES platform are improving settlement speeds, lowering denial rates, and reducing working-capital pressures for providers, strengthening the underwriting case for scaled provider networks and enabling services tied to reimbursement performance.
Technology-enabled care and hospital “backbone” systems have become another investable layer alongside hospitals and clinics. Deal Flow Analysis notes the Sehhaty mobile health application has over 24 million users, about 68.5% of the population, supporting appointment scheduling, teleconsultations, prescription management, and health tracking. It also cites Expert Market Research valuing the Saudi Arabia healthcare asset management market at USD 1.13 billion in 2024, forecast to reach USD 6.60 billion by 2034 at a 19.30% CAGR. On the build side, MarkNtel Advisors reports investments exceeding USD 8.4 billion announced in new hospital projects and infrastructure developments through public-private partnerships. Together, these signals explain why Saudi healthcare private equity increasingly pairs M&A with digital rollouts and operational tooling that standardizes performance across acquired sites.
What policy targets are shaping private investment in Saudi healthcare?
Why are mid-sized clinics a common focus in Saudi provider consolidation?
How does insurance market structure influence deal theses in the Kingdom?
What role does digital adoption play in Saudi healthcare investment strategies?
How is Saudi healthcare private equity evolving beyond hospital acquisitions?