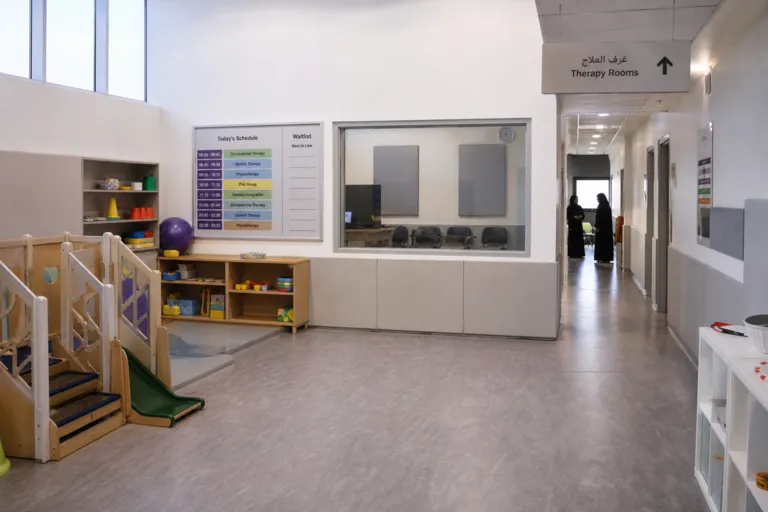
Early support is becoming central to how Saudi Arabia plans autism care. A Saudi Medical Journal study cited in 2026 reporting estimates that autism spectrum disorder (ASD) prevalence among children in the Kingdom is between 1.7% and 1.8%, which is higher than the currently cited figure of 0.6%. The study draws on international and regional comparisons and adjusts for local factors like diagnostic practices and healthcare access. That shift in baseline demand matters because it implies more children need screening, diagnosis, and ongoing support than planning may have assumed, especially when services are unevenly accessible.
Against that demand backdrop, the Saudi ASD treatment market is projected to expand. Grand View Research estimates that Saudi Arabia’s autism spectrum disorder treatment market generated USD 13.0 million in revenue in 2025 and is expected to reach USD 20.5 million by 2033, with a projected CAGR of 5.9% from 2026 to 2033. In 2025, Saudi Arabia accounted for 0.5% of the global autism spectrum disorder treatment market in revenue terms. The same outlook projects Saudi Arabia to lead the Middle East & Africa regional market in revenue in 2033. These figures point to momentum, but revenue growth does not automatically close service gaps in diagnosis and day-to-day intervention.
Where the Capacity Gap Shows Up: Access, Channels, and Care Mix
The capacity gap is often felt first in practical access: how quickly families can obtain a diagnosis and then secure consistent therapy and follow-up. The 2026 prevalence analysis explicitly calls for revised public health planning, stronger early screening initiatives, and better resource allocation for autism services, while also urging action to address geographic disparities outside major cities. Market signals echo this need for scalable delivery. A separate global market analysis notes that countries including Saudi Arabia are investing in early diagnosis, digital health solutions, and specialized intervention centers, and that telehealth platforms can be particularly impactful in remote areas by addressing a significant treatment gap.
Within the treatment market mix, medication remains a large revenue component. Grand View Research reports that antipsychotic drugs were the largest segment in Saudi Arabia in 2025, with a revenue share of 43.85%, and the same segment is also described as the most lucrative and the fastest growing during the forecast period. Distribution channels tracked for Saudi Arabia include hospital pharmacy, retail pharmacy, and online pharmacy. This structure matters for capacity because it highlights that treatment spending may skew toward pharmacological management, while families also seek behavioral, developmental, and educational supports that determine everyday outcomes and require specialist time and service availability.
International comparisons provide context for why early detection keeps rising as a planning priority, even when local systems face constraints. In the U.S., the Centers for Disease Control and Prevention reported in May 2025 that about 1 in 31 children aged 8 years (3.2%) had been identified with ASD, and that identification occurred across racial, ethnic, and socioeconomic groups, with autism more than three times more common among boys than girls. Saudi decision-makers are not being asked to copy another country’s baseline, but the comparison underlines why stronger monitoring and capacity-building matter. For the Saudi autism services market, the practical goal is to align screening, diagnosis, and support pathways so that higher estimated prevalence translates into timely help rather than longer waits.
What is the estimated autism prevalence among children in Saudi Arabia?
How is Saudi Arabia’s autism spectrum disorder treatment market expected to grow?
Which treatment type led revenue in Saudi Arabia in 2025?
What kinds of solutions are highlighted for closing gaps in access to care?
What is driving urgency in the Saudi autism services market’s capacity planning?