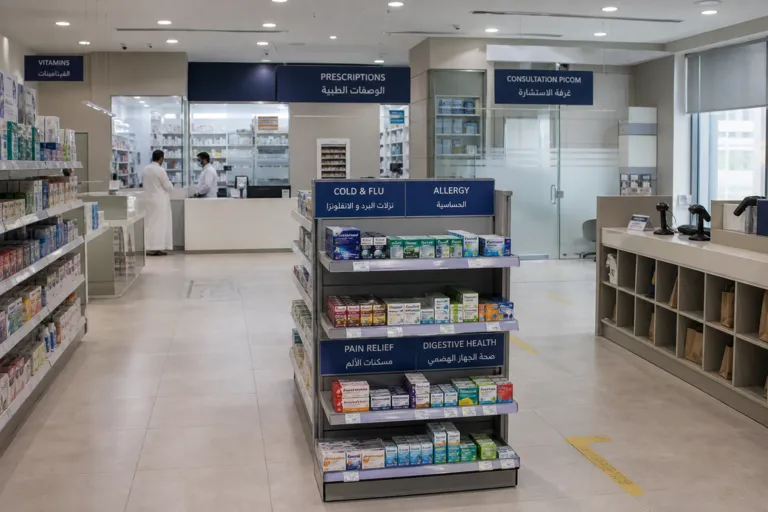
Rx-to-OTC switches are changing what shoppers can buy without a prescription. Sources tracking global OTC trends link this shift to regulators relaxing rules that once kept more complex molecules in prescription-only channels. One report describes growing regulatory acceptance of prescription-to-OTC switches, especially for chronic yet self-manageable conditions, as a key trend that expands long-term self-care options. For Saudi Arabia’s consumer health landscape, this matters because it supports the same shopper goal that also underpins global growth: self-treating minor ailments, while simplifying decisions at the shelf and in digital channels.
In Saudi Arabia, the OTC pharmaceutical market size reached USD 1,738.7 million in 2025, with IMARC projecting USD 2,743.4 million by 2034 at a 5.20% CAGR during 2026–2034. The same source links growth to heightened health awareness, a transition toward self-medication, and better availability through pharmacies and websites. That behavior is visible in survey data: a study of 1,671 people across areas of Saudi Arabia found 75.5% practiced self-medication, mostly occasionally. In this context, the Saudi OTC drugs market is not only about volume; it is also about trust, access, and which conditions consumers feel comfortable managing without a doctor visit.
Rx-to-OTC Switches: What the Global Pipeline Signals for Saudi Retail
Internationally, Rx-to-OTC conversion activity offers a window into which categories can expand next. Market Growth Reports states that in 2023, 14 medications were reclassified from prescription-only to OTC in Europe and North America, boosting availability for areas including allergies and acid reflux. Another global report frames the same structural direction: regulators are continuing to relax rules, encouraging manufacturers to rethink lifecycle strategies for mature brands and to add digital self-selection tools at launch. Saudi Arabia should not be assumed to mirror foreign approvals, but these figures show a consistent global mechanism: reclassification can shift demand from clinics to the shelf, and widen consumer choice.
Channel evolution makes that access more immediate, especially online. IMARC reports Saudi Arabia’s e-pharmacy market reached USD 969.3 million in 2024 and is expected to reach USD 3,037.5 million by 2033, at a 12.1% CAGR during 2025–2033. It attributes adoption to rising smartphone penetration and internet connectivity, and notes convenience features such as doorstep delivery and prescription management options. This matters for OTC because online stores can display a wider product portfolio than physical stores, supporting discovery of newly switched products and established OTC staples alike, while helping shoppers compare formats and instructions before purchase.
Saudi Arabia also plays an outsized role inside the GCC OTC landscape. IMARC’s GCC OTC drugs forecast states Saudi Arabia led the regional market with around 47.5% share in 2025, supported by new retail pharmacy outlets, government initiatives tied to OTC availability, and strong e-commerce presence. Yet prescription therapies still dominate the wider national pharmaceutical mix. Future Market Insights expects prescription products to lead the Saudi Arabia pharmaceutical market with a 61.6% share in 2026. Together, these points suggest a dual reality: prescriptions remain central for long-course therapies, while OTC growth is reinforced by self-care behavior and by the kinds of reclassification pathways that move select treatments from prescription status to front-of-store and online shelves.
How big is Saudi Arabia’s OTC pharmaceutical market, and what is the outlook?
What evidence shows self-medication is common in Saudi Arabia?
What do Rx-to-OTC switches look like in other regions?
How fast is Saudi Arabia’s e-pharmacy market growing?
What is Saudi Arabia’s role in the Saudi OTC drugs market story within the GCC?