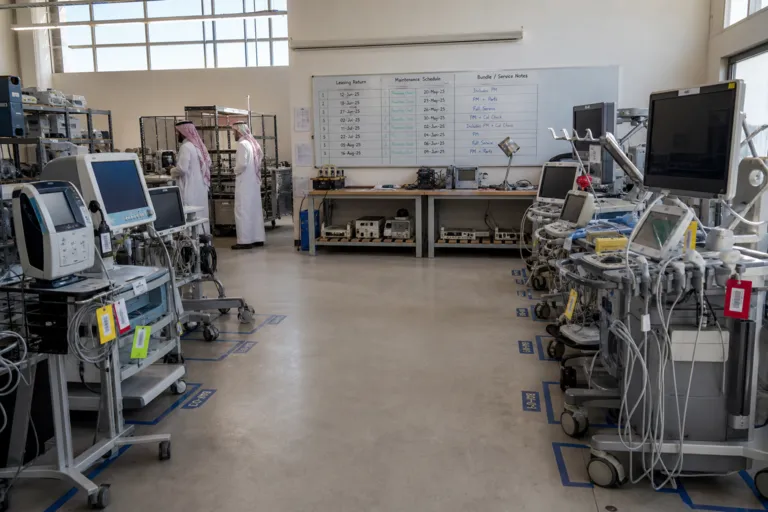
Saudi hospital CAPEX planning is being pushed in two directions at once. On one side, Vision 2030 health and social development allocation reached SAR 260 billion in the 2025 budget, a 12% increase from the previous year, supporting 12 new medical cities and upgrades to 150 existing facilities. On the other, procurement is becoming more demanding and solution-driven. IndexBox notes that for capital equipment, the listed price is only a starting point, with negotiations expanding into financing options such as leasing and pay-per-procedure models, plus service terms and training packages. That shift helps explain why access can start to matter more than ownership when hospitals need to modernize without creating large upfront spikes.
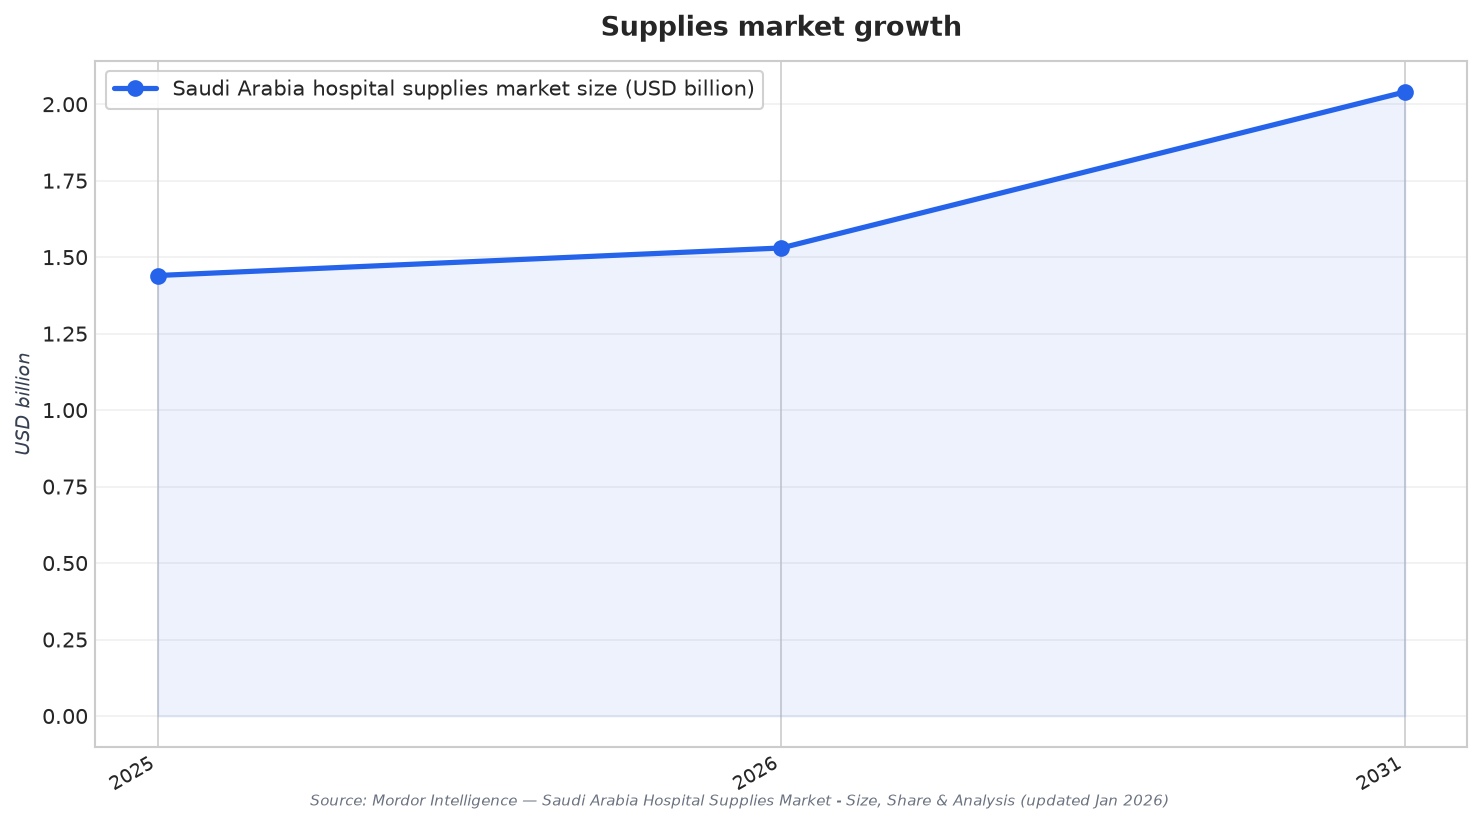
The scale of near-term demand also adds pressure to rethink ownership-heavy buying. Mordor Intelligence projects the Saudi Arabia hospital supplies market to expand from USD 1.44 billion in 2025 and USD 1.53 billion in 2026 to USD 2.04 billion by 2031, at a CAGR of 5.92% from 2026 to 2031. Hospitals accounted for 64.38% of spending in 2025, while operating-room equipment is projected to grow at a 7.73% CAGR through 2031. Mordor also highlights a national goal to add 27,000 beds by 2030. As these commitments stack up, leasing can work as a release valve for CAPEX, shifting parts of equipment acquisition into structured payments paired with service expectations.
Why Asset-Light Models Fit Saudi Procurement Reality
Technology cycles make ownership riskier, especially for high-spec systems. Mordor’s healthcare equipment leasing report states that high-spec imaging and therapy systems evolve every two to three years, which supports leasing as a pathway to modernization without large CAPEX spikes. That same report frames a broader move toward asset-light operating models, including full-service approaches that can bundle training and analytics support. In Saudi Arabia, IndexBox similarly describes procurement moving from product-centric to solution-centric offerings that bundle capital equipment, consumables, software, and service into single value-based contracts. In that context, Saudi medical equipment leasing becomes less about financing alone and more about buying a performance-backed capability that can be refreshed as standards and workflows change.
External market context also shows how quickly leasing models are scaling, even though those figures are global rather than Saudi-specific. Verified Market Reports estimates the global medical equipment leasing service market at USD 12.5 billion in 2025, forecasting USD 20 billion by 2034 at a 6.5% CAGR from 2026 to 2034. A separate Verified Market Reports estimate puts the broader global medical equipment leasing market at USD 175.18 billion in 2025, projected to reach USD 406.85 billion by 2034, at a 9.81% CAGR from 2026 to 2034. For Saudi decision-makers, these numbers function as a comparison point that aligns with the local shift toward financing options, managed equipment services, and pay-per-use structures described by IndexBox.
Saudi procurement reforms and clinical demand add more reasons to prioritize access. Mordor points to diabetes affecting 18.5% of adults and cardio-metabolic disorders accounting for more than one-third of deaths, trends that intensify consumption of monitoring devices and other hospital supplies. It also notes NUPCO’s digital marketplace can shorten tender cycles, while ISO 13485 compliance remains mandatory for devices entering NUPCO tenders. At the same time, IndexBox describes consolidation under government-led mega-tenders and the influence of private hospital chains. In this environment, leasing and flexible commercial models can align equipment refresh, compliance, and service readiness into one contract while keeping CAPEX planning more predictable.
Why are Saudi hospitals looking beyond equipment ownership?
What local signals suggest demand pressure on hospital investment plans?
How does Saudi medical equipment leasing connect to fast-changing technology?
What does Saudi procurement evolution mean for leasing contracts?
Are there global benchmarks that illustrate leasing momentum?